The Ethereum mainnet used to be the hub of all on-chain activity. However, with the growth of alternative execution layers (particularly Base and Solana) and many other L1/L2s contending for users, Ethereum’s role has arguably diminished, particularly in recent months.
Ethereum is still #1 in TVL by a wide margin. Per DeFiLlama, it is over five times larger by this metric than the second-largest blockchain, Solana, and 53.9% of all stablecoins are on Ethereum. On the other hand, in 30-day DEX volumes, Solana is at $265bn vs. $93bn on Ethereum. Base is at $51bn and consistently increasing its market share.
Most notably, Ethereum is no longer the most fee-generating protocol, ranking 9th with individual applications like Uniswap, Jito, Raydium, and PancakeSwap overtaking it in recent months. This combined with lackadaisical price action has driven a discussion on what exactly Ethereum’s role and the value of ETH, the asset, will be in the future. If transaction execution (i.e. users and usage) moves to other chains (including L2s), how does ETH capture value?
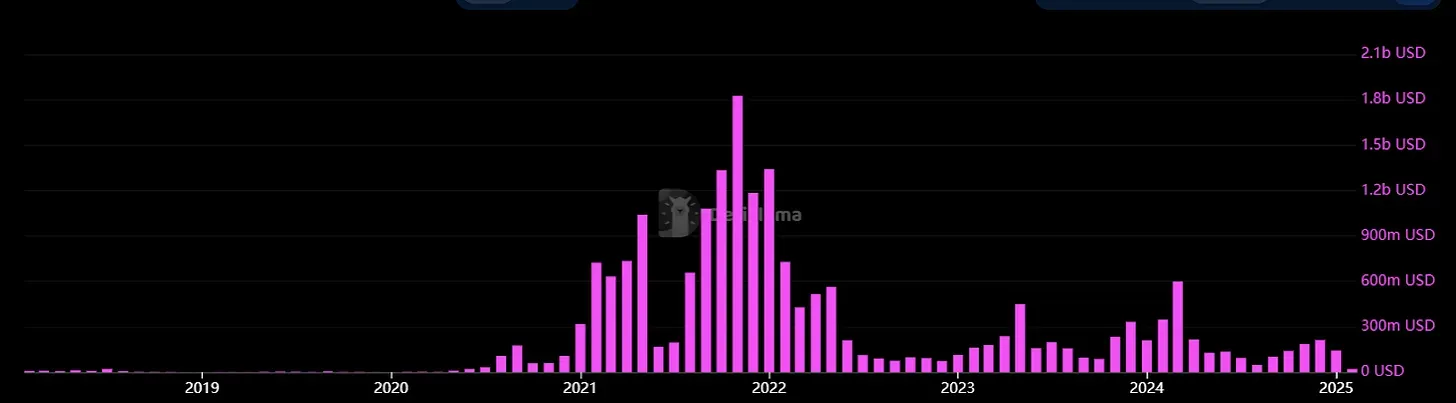
Ethereum, fees generated per month. Source: DefiLlama.
Now, it’s possible to argue (and some do) that Ethereum captures enough value from its “moneyness” and fees from data blobs posted by L2s. The money aspect is a very different argument and outside the scope of this blog post where we are discussing fees and valuing blockchains by some reasonable multiple relative to them.
To take a step back—when Ethereum was launching—it’s worth remembering that the idea of what businesses would look like on blockchains was quite different from today’s. The idea was that blockchains and the core functions facilitated by them would be viewed more as Internet protocols than businesses. Money transfer and other related functions are like TCP/IP, but they touch value, not just information.
Vertical (or horizontal) integration across the stack doesn’t make sense in that context. The exchange protocol will handle asset exchange, the oracle protocol will bring in outside information, and the lending protocol will be used for – well, lending. Protocols doing other things apart from their core function violate the “credible neutrality” of an Internet protocol.
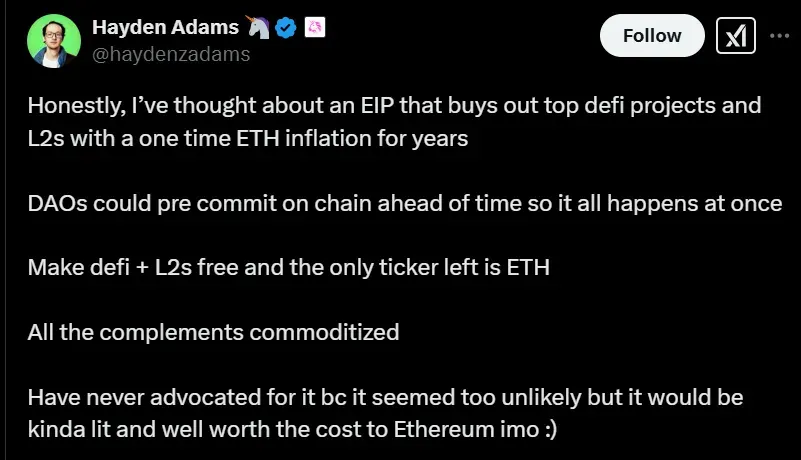
X Post by Hayden Adams, founder of Uniswap.
Messy real-world incentives burst this pretty picture. In practice, most major DeFi protocols will extend out to multiple functions – lenders become stablecoin providers (e.g. Aave), liquid staking gets mixed in with the MEV supply chain (e.g. Jito), and bridge providers become exchanges. It’s not far-fetched to imagine a single protocol with one token that is an execution layer, a data-availability provider, an exchange (spot and derivatives), a liquid staking service, and a lending/stablecoin platform. This was (to a degree) the vision behind the Canto blockchain.
Crypto is just like any other business. The incentive to go after new markets to create more value for tokenholders is clear. And with other businesses encroaching – either purposefully or not, this is also by design if you build a chain with L2s in mind – on Ethereum’s “territory”, a natural response is to push back.
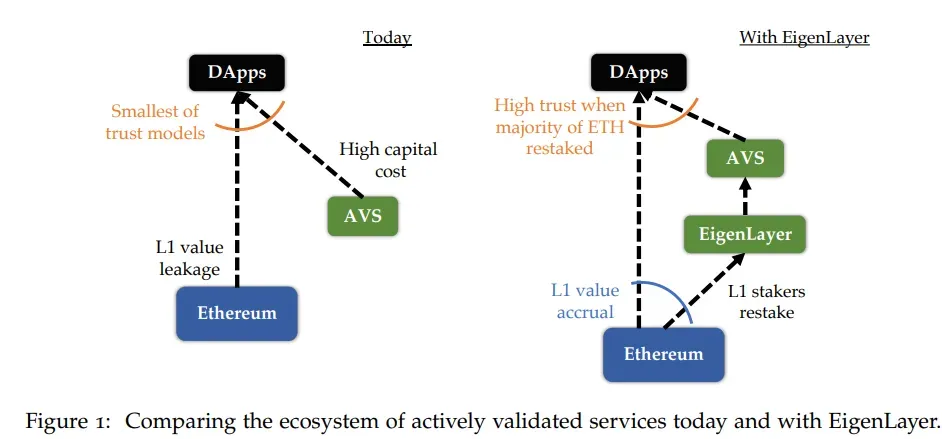
Illustration from the EigenLayer whitepaper.
EigenLayer, and the subsequent growth in attention and funding for other restaking projects, is arguably a type of response by the market to extend out Ethereum’s features and drive more value to ETH. Instead of “requiring” a new token to secure an oracle, L2, or token bridge, all you need is ETH. One can make fanciful arguments around economic security that make for long whitepapers (more common in 2017 than today) but expanding the functionalities of ETH is the core argument for restaking systems.
2 weeks ago, Justin Drake published a proposal on “Native Rollups”. In short, this enables direct L1 execution integration. Instead of running a separate virtual machine (VM) or relying solely on off-chain computation, native rollups would leverage the L1’s native execution engine. A new precompile to verify EVM state transitions for batches of user transactions. Soon, you’ll also see “Based Rollups” coming to market where MEV naturally flows to L1 validators. There’s a longer discussion to be had about what features and limitations this locks in and what the economics are for L2s, but in short, these ideas drive more transaction and MEV fees to ETH holders.
Here’s a prediction: in the next 6 months, there will be a high-profile fundraise for an “ETH Maxi L2”. This L2 will fork the major (mostly ossified) protocols in DeFi and turn on all fee switches, driving both application and sequencer revenue to ETH holders. The promise is that there will not be a native token and a portion of the fees generated go to the founding team for development and as incentives. As the technology for building L2s matures, go-to-market is more important than technical differences that are becoming ever-less distinctive. “ETH Maxi L2” is a potentially viable go-to-market strategy.
Native and Based Rollups, restaking, and the reinvigorated enthusiasm to increase gas limits to increase execution capacity are all examples of the Ethereum community (and ETH holders) “fighting back” and increasing Ethereum’s role in transaction activity. On the other hand, rollups that drive value to ETH holders are also in direct competition with those that don’t – and that’s not entirely “credible neutral” activity.